

Hey all, Jason here.
My apologies for the sub-optimal weather to folks who made the trip from the U.S. to Amsterdam for Money20/20 — the week before you came was the best possible late spring weather you could ask for here! Try again next year, I suppose.
For my AML, data and agentic AI folks, Castellum.AI is hosting a webinar later this month on “The Data Foundation: Driving Effective AI Agents in AML.” With speakers from Stripe, FinWise, and Hummingbird, it looks like a can’t-miss session.
Business Banking That Actually Works Globally
Partner content: Limited gives your business bank accounts in the US, Europe, Latin America, Africa, and MENA from one platform.
Issue expense cards, manage team spending, and pay out to vendors and contractors through 300+ local payment rails in 80+ currencies, not just SWIFT. That means faster settlement, lower fees, and no more waiting days for a cross-border wire to land. Your funds are held in your own custody, never pooled, never exposed to someone else’s risk.
Join multinational companies that already use Limited to manage spending, pay global teams, and move money without friction.

Sen. Warren, CFPB Pressure Bilt to Compensate Users Impacted by Rocky Transition
Neighborhood loyalty and rewards startup Bilt seems to have largely resolved the issues that frustrated some users as it migrated to its “Bilt 2.0” offering.
During that transition this February and March, users took to social media to voice complaints about a variety of problems they were experiencing, including:
Users who were declined for the new card or received a credit limit substantially lower than they had previously;
What users viewed as an excessively complicated rewards earning and redemption structure;
Users experiencing declined transactions and frozen cards, including during a promotional period when Bilt was offering a higher rate of points on certain transactions;
Users who claim outstanding balances were transferred from Wells Fargo to the new cards without their permission;
Users who complain they’ve experienced difficulties making payments on outstanding balances still held at Wells Fargo;
Users who claim they received a new Wells Fargo Autograph card they didn’t want or authorize;
Users who say older statements they needed for financial tracking/planning and tax prep disappeared from the Bilt app;
Users who believe they should have qualified for a special promotion offered if they signed up for Bilt 2.0 through a link on The Points Guy website, but didn’t;
Users who reported difficulty in linking bank accounts to Bilt;
Users who reported not receiving their physical Bilt card or receiving it with incorrect/incomplete details printed on the card;
and, perhaps the issue that drove the most frustration and outrage, issues with rent and mortgage payments not being made, being delayed, or bouncing, with some users reporting their external bank account had been debited by Bilt, but the corresponding payment was never made to their landlord or mortgage servicer.
Bilt users who raised issues through the company’s app reported frustrating and, at times, nonsensical interactions with Bilt’s AI-powered customer service chatbot. Those trying to reach a human Bilt support representative could only do so via email and many reported days-long waits to get a response.
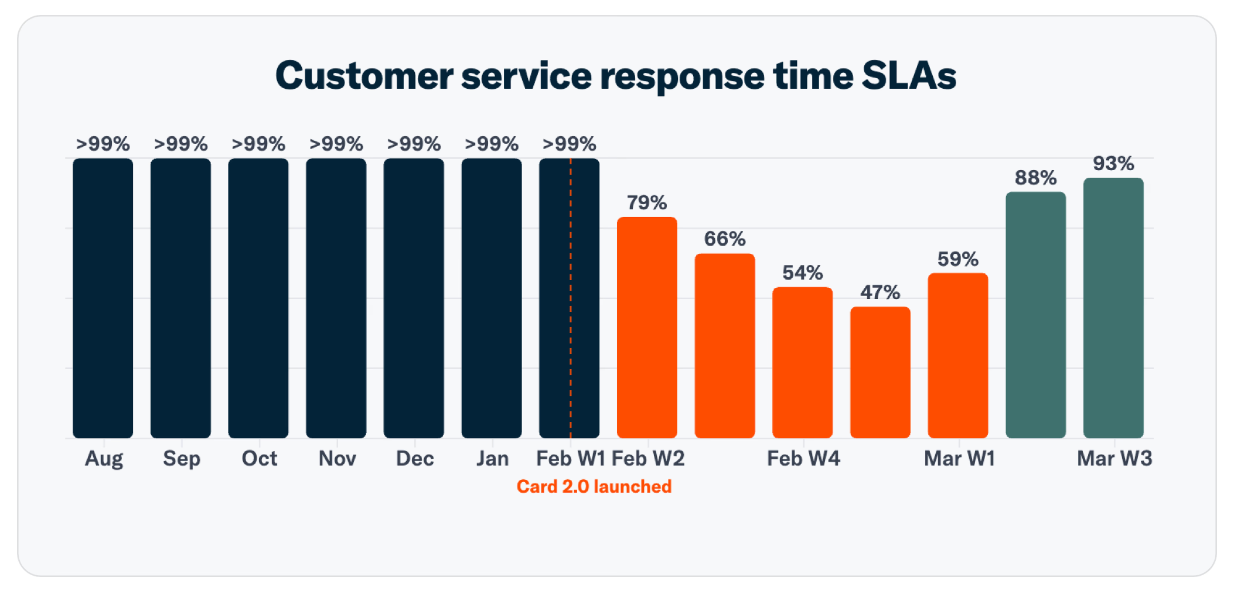
With the number of service providers in the mix — Column as Bilt’s new card issuer, Cardless as its new servicer, plus the legacy Wells Fargo accounts and newly issued Wells Fargo Autograph cards — some users were frustrated by what they perceived as finger pointing between the various firms’ customer service teams, with seemingly no one taking responsibility for resolving users’ issues.
The Bilt situation caught the attention of Senator Elizabeth Warren (D-MA), the ranking member on the Senate Banking Committee, who sent Bilt a letter (which extensively cites Fintech Business Weekly’s reporting) at the end of May over how the company has handled the rocky transition and its impact on users.
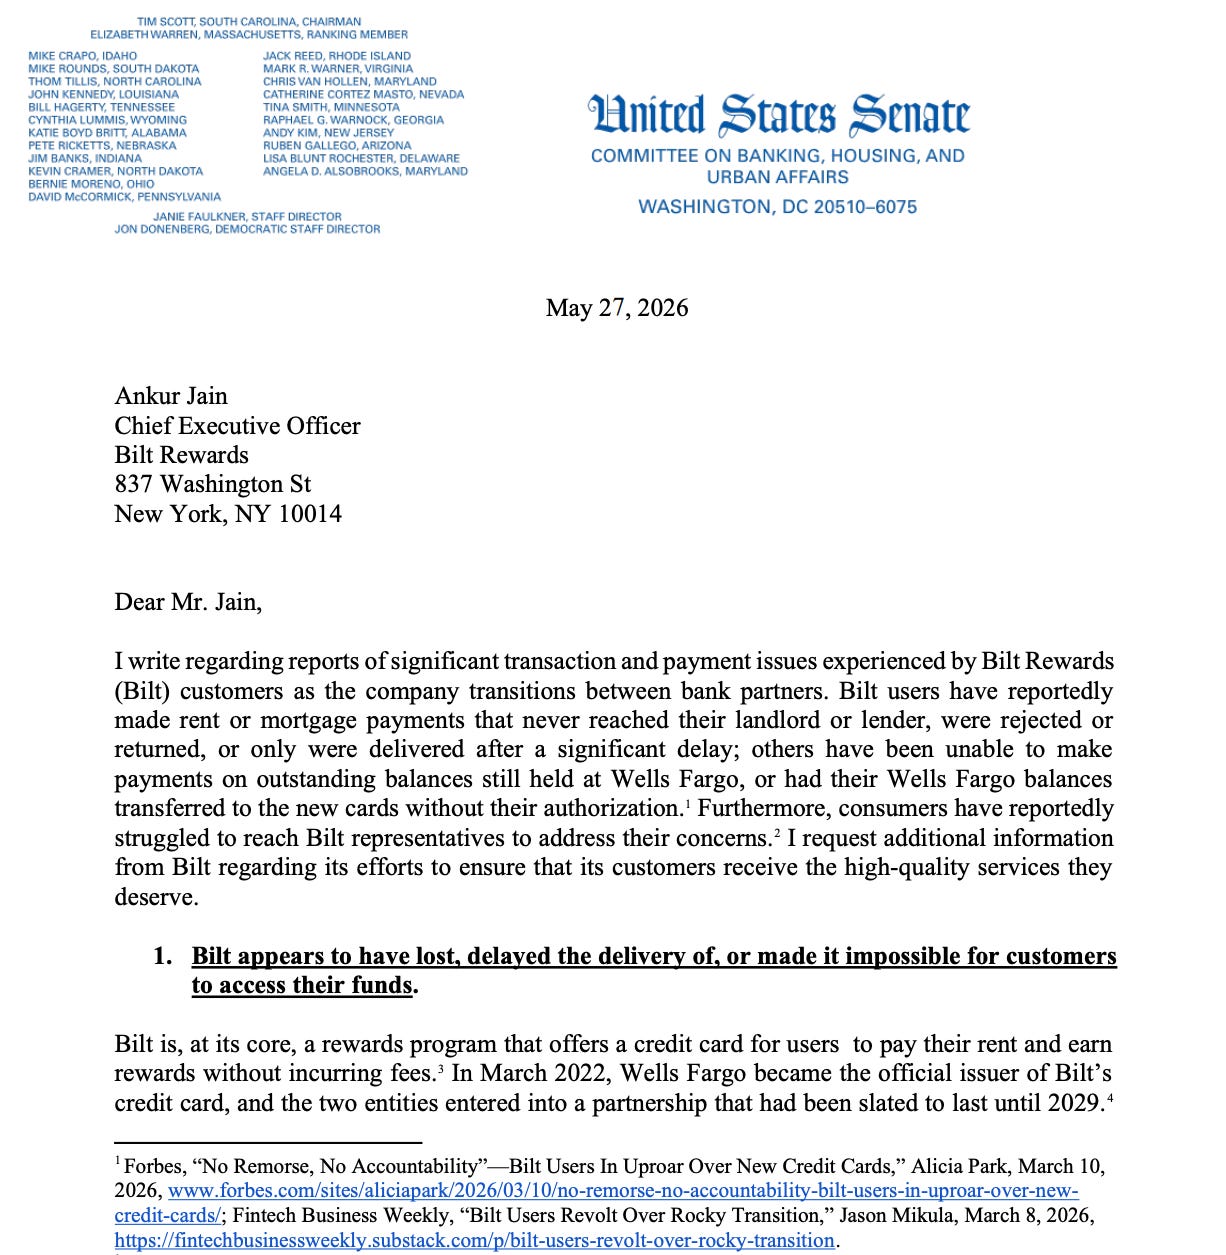
Warren’s letter to Bilt CEO Ankur Jain poses questions on a number of areas of potential consumer harm:
Bilt appears to have lost, delayed the delivery of, or made it impossible for customers to access their rent or mortgage funds.
Bilt is now partnering with Evolve Bank, which was at the center of a major scandal involving nearly $100 million in lost customer funds in 2024.
Bilt 2.0 immediately debits rent payments, raising questions about compliance with the Credit CARD Act of 2009.
Bilt’s use of an AI chatbot has made it inaccessible to consumers and appears to provide terrible customer support.
People familiar with Bilt’s program told Fintech Business Weekly that Bilt has been steadily winding down its relationship with Evolve since 2022. The most recent terms and conditions posted on Bilt’s site, updated last week, make no mention of Evolve.
Warren’s letter requests a variety of information and data from Bilt, including:
Bilt’s understanding of what may have led to customers experiencing allegedly lost, delayed, or returned housing payments and how Bilt has responded to each issue;
What steps Bilt intends to take to improve its customer service;
How Bilt’s new card and housing payment practices are compliant with the CARD Act of 2009;
The number of customers who had a rent or mortgage payment debited from their account that was not returned to the customer or delivered to their landlord or lender as of April 30, 2026, and the total dollar amount of such payments;
The number of customers who had a rent or mortgage payment debited from their account that was later returned to the customer and the total dollar amount of such payments;
and the number of customers who had a rent or mortgage payment debited from their account that was not delivered to their landlord or lender within 72 hours and the total dollar amount of such payments.
In a highly unusual move, the Consumer Financial Protection Bureau — itself the brainchild of Warren, before she became a Senator — weighed in publicly, releasing a brief statement on its website about how the CFPB is addressing the Bilt situation.
The statement, published on Tuesday, June 2nd, says in part (emphasis added):
The CFPB has been working to ensure consumers affected by Bilt’s transition to a new bank partner are appropriately remedied. CFPB officials met with Bilt to understand the issues caused by the transition and what steps Bilt has taken to ensure customers affected by challenges with the transition were made whole.
Following our discussions and at our direction that Bilt ensures full redress, Bilt notified the CFPB that they proactively reached out to the limited number of potentially-affected customers and offered to reimburse them for any overdraft fees, late fees, or insufficient funds fees related to the transition.
The CFPB has also discussed with Bilt the steps it has taken to guarantee that all transition-related technical issues have been resolved, and Bilt’s documentation submitted to the CFPB appears to show that it has completed the process and its systems are back on track.
The CFPB statement further noted that “Bilt is in the process of reviewing requests for reimbursement and, by June 4, will reimburse fees for more than 500 newly identified customers from its outreach following discussions with the CFPB.”
The CFPB’s public statement is notable — and unusual — for a number of reasons, not the least of which is that the bureau has become a shell of its former self under acting Director Russ Vought.
The only public enforcement action the CFPB has taken under the current administration has been the pro forma case against bankrupt middleware provider Synapse. Indeed, the CFPB has watered down and rolled backed numerous enforcement actions, terminated consent orders, and closed ongoing investigations.
It’s also worth noting that the CFPB does not have supervisory jurisdiction over Bilt, though that wouldn’t preclude the bureau from bringing an action using its UDAPP authority.
Multiple industry experts, including former CFPB staffers, told Fintech Business Weekly that it wasn’t necessarily unusual that the CFPB would meet with a company regarding alleged consumer harm — particularly one as large and high-profile as Bilt, which has generated significant media attention.
But, industry experts stressed, issuing a press release about such a meeting is largely unprecedented.
Taking the CFPB’s statement at face value, it should interpreted mostly as a positive: the bureau, like Senator Warren, appears to be working to ensure that Bilt makes things right with consumers who were negatively impacted by issues the company experienced in its transition.
For its part, a Bilt spokesperson reiterated the company’s focus on its users, sharing the following statement with Fintech Business Weekly:
Our members have been our priority since day one. While the transition to the Bilt Card 2.0 in February represents an even more exciting future that offers our membership richer rewards and greater flexibility, the transition also attracted unexpectedly high demand, and some of our members experienced gaps in service that are simply unacceptable to us.
In response, we increased our customer service capabilities to address this and proactively communicated with any impacted members. All outstanding issues relating to the card transition in February have been addressed and resolved.
Should any member ever have an issue we encourage them to contact Bilt, as we will do everything we can to make it right.

Bolt’s Breslow Made Headlines For “Firing HR.” Now He Claims Bolt “Has Achieved Profitability,” Despite Unpaid Bills.
Ryan Breslow, the volatile cofounder and once-and-again CEO of one-click checkout / “super app” Bolt, made headlines last month when he announced at a workforce innovation summit that he had “let go” the company’s entire HR team for “creating problems that didn’t exist.”
Breslow added that Bolt replaced the HR function with “a couple of person people ops team” that he described as better suited to the company’s return to functioning more like a “gritty” startup.
But now-former Bolt staffers pushed back on Breslow’s characterization that he “let go” of those working in HR.
The company’s former Senior Vice President of Legal and People Olta Andoni wrote in a public post, “Since Bolt’s CEO chose to disparage me publicly, I feel compelled to set the record straight. As the former SVP of Legal and People at Bolt, I made the decision to resign after one month with the company. My resignation was also publicly reflected on my LinkedIn profile. Additionally, former Head of HR… left the company five days after I joined to pursue another better opportunity.”
And Bolt’s former revenue accounting manager Paul van der Stam also commented publicly on Breslow’s claims, writing, “One correction to the public record: the HR and People Ops team were not fired. Each person left on their own volition. Ryan’s characterization is not only inaccurate, it is disparaging to people who made an integrity-based choice.”
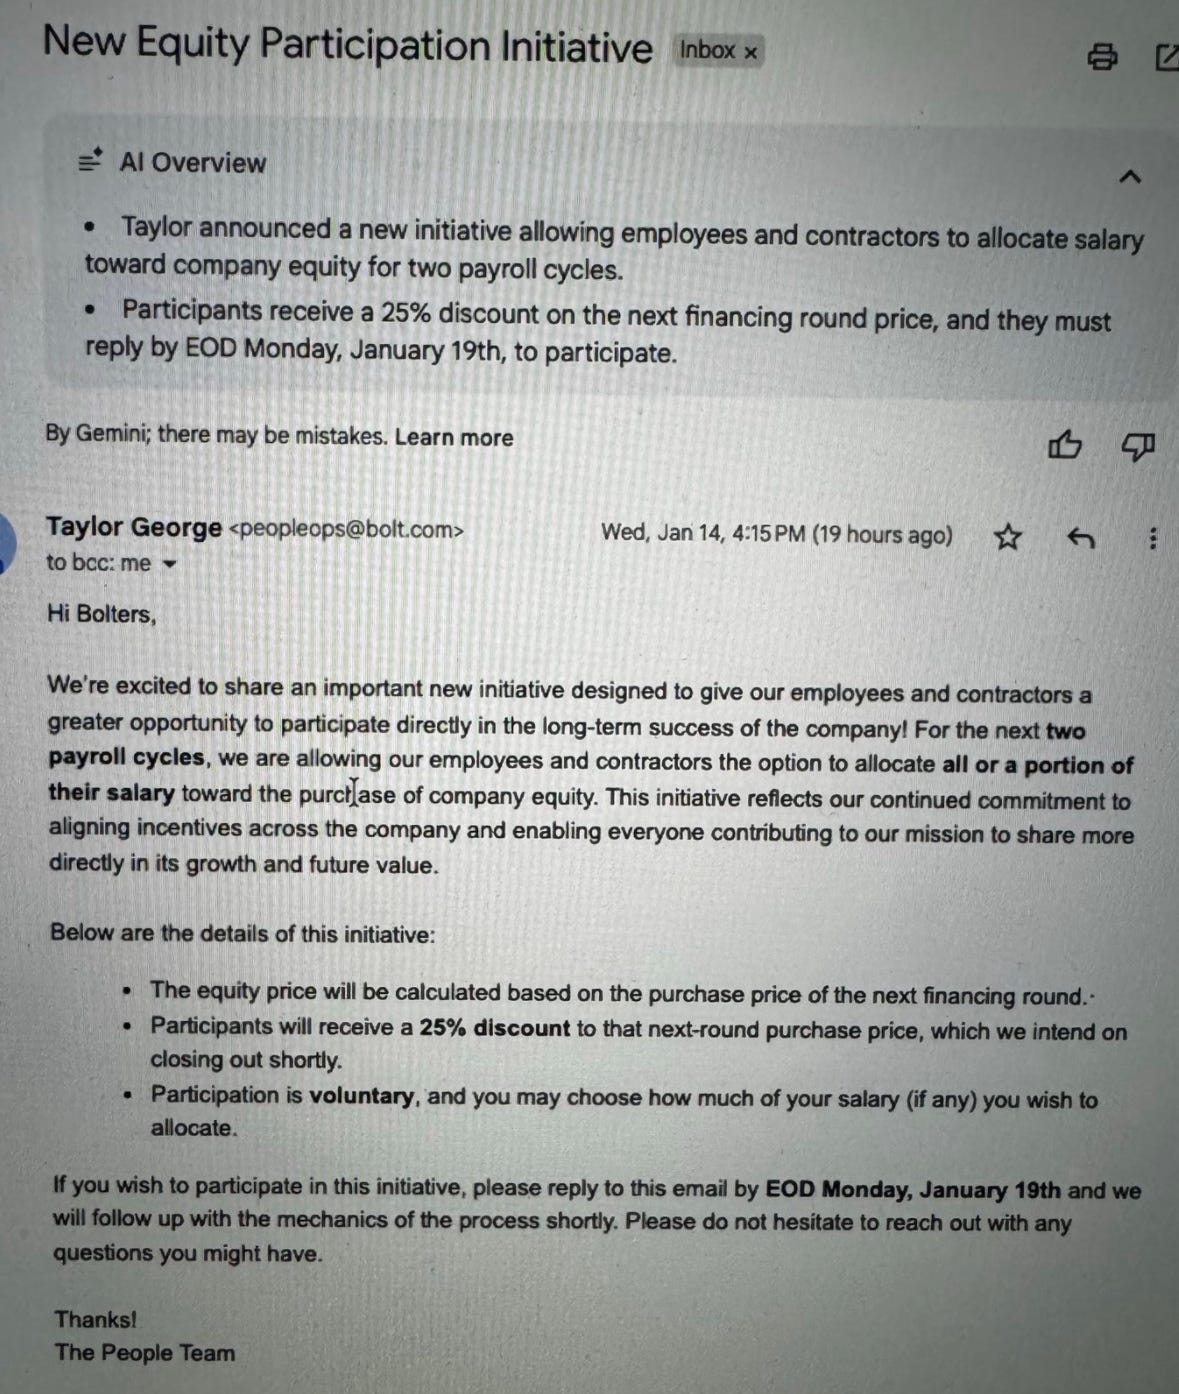
During Breslow’s interview at the HR conference, Fortune’s Kristin Stoller asked Breslow about what Stoller described as “rumors” that some of Bolt’s independent contractors hadn’t been paid since January 2026 and that employees were offered equity in lieu of salary — information originally reported by Fintech Business Weekly that Bolt representatives had the opportunity to comment on or dispute prior to publication.
Breslow responded to the question about the “rumors” of non-payment and offering Bolt equity in lieu of staffers’ normal paychecks by saying, “We’ve had to make a lot of tough decisions once again as a startup that have resulted in some of those rumors spreading. Those specific ones that you’ve listed, no, that’s not the case.”
Asked to clarify the situation, a Bolt spokesperson commented to Fintech Business Weekly last Tuesday, writing, “Everyone who is doing their work has gotten or is getting paid” — seemingly confirming that there are Bolt contractors the company has not paid.
Breslow also denied that staffers were offered equity instead of their normal pay, despite supporting evidence shared with Fintech Business Weekly that seemingly contradicts Breslow’s statement:
Perhaps more shocking than Breslow’s HR comments is his claim that, “for the first time since inception, Bolt has achieved profitability.”
Breslow made the assertion in a lengthy social media post last week, where he wrote in part:
Last month, Bolt’s gross profits hit an all-time high while OPEX reached a record low.
Bolt has been doubling down on decisions that emphasize long-term profitability and market share capture. We have been investing heavily in our checkout, payments, and 1-click platform, which allow us to compete with $100b+ incumbents and win deals on a consistent basis.
We are winning deals on cost, conversion, and customer support.
We’ve also launched over 20 new product lines that have expanded our portfolio of fee capture, increased stickiness with customers, and improved customer satisfaction.
We have not been afraid to make the hard strategic decisions on reorganizing our teams. For instance, we have eliminated our Account Management and Implementation Management teams entirely. Now, sales reps manage customer relationships from beginning to end, and their only counterparts are highly technical engineers. No other non-technical middlemen. Our customers say the attention they’ve received is 10x what it has been historically, and the team has never felt more empowered and motivated.
These tough decisions have allowed us to cut OPEX considerably while driving record levels of revenue. Our integrations queue is currently filled to the brim.
Startup founders and CEOs have a way of bending the definition of “profitability” (we all remember community-adjusted EBITDA, right?), but a source close to Bolt that is familiar with the company’s financials claims that Breslow is referring to GAAP profitability.
Fintech Business Weekly could not independently verify the source’s claim, but it is somewhat difficult to reconcile with other newly obtained information and internal company communications.
As of late April, the company had failed to pay a $40,467 invoice from subscription billing platform Chargebee, which was due on January 6, 2026. Bolt was eventually locked out of the ability to login or manage its Chargebee services due to non-payment, according to internal documents shared with Fintech Business Weekly.
Bolt has also failed to file corporate income tax returns in Canada for 2020, 2021, and 2022, according to internal communications reviewed by Fintech Business Weekly. Bolt staffers estimated the company’s unpaid tax liability at approximately CAD $500,000 (about USD $360,000).
Fintech Business Weekly asked the Bolt spokesperson about the Chargebee and Canadian tax issues, but did not receive a response as of the time of publication.
Everyone Wants To Issue Their Own Stablecoin. But Is It Sustainable?
Stablecoin-related announcements seem to be reaching an absolute fever pitch lately. In just the past week or so, we’ve seen:
Cash App rolled out support for USDC to its nearly 60 million users
SoFi announced (for what feels like the umpteenth time) that its 15 million members can now buy, sell, hold, and convert its SoFiUSD stablecoin
Reports circulated that Stripe, Visa, Mastercard, and, potentially, Coinbase may team up on issuing a new stablecoin
MoneyGram announced its MGUSD stablecoin
Deel announced its DLUSD stablecoin
Big-bank payments consortium The Clearing House is developing a tokenized deposit network
And the Conference of State Bank Supervisors published a comment letter on the Treasury’s proposed principles for assessing state-level regulatory regimes
Cash App began rolling out its USDC stablecoin feature to users toward the end of May. All users should now have access to these capabilities.
The move is notable because Cash App parent company Block and its cofounder and CEO Jack Dorsey have, historically, been more narrowly focused on bitcoin, when it comes to crypto.
Cash App’s USDC support is relatively narrowly limited to operating as a pay in/pay out rail.
Cash App users can deposit USDC into their Cash App accounts via the Solana, Ethereum, Polygon, and Arbitrum blockchains — but these funds are immediately converted to fiat US dollars, not held within Cash App as stablecoins. Conversely, users can withdraw fiat funds from their Cash App wallets as USDC into wallets on the aforementioned blockchains.
SoFi’s approach is a notable contrast to Cash App. SoFi has chosen to create its own stablecoin, SoFiUSD, which, the bank says, is redeemable 1:1 for fiat US dollars and is fully backed by “liquid assets.” SoFiUSD operates on Ethereum and Solana.
SoFi says that in the “coming weeks” users will be able to convert SoFiUSD into tokenized deposits, “allowing members to earn interest and access FDIC insurance on the deposits.” SoFi also intends to offer “global mobility” on the blockchain, which, the bank says, will “allow[] SoFi members to move value across borders 24/7/365, with fewer delays and lower costs than typical legacy financial systems.”
SoFi plans to launch SoFiUSD on crypto exchange Bullish, thereby making it available to institutional clients and supporting stable pricing and efficient execution for high-volume trades.
It’s not clear why a typical SoFi retail accountholder would need or want to hold SoFiUSD (and/or the bank’s planned tokenized deposit product.)
Industry analysts Ron Shevlin and Alex Johnson offer two plausible theories.
In his Fintech Snark Tank newsletter, Shevlin argues that the retail rollout of SoFiUSD is something of a test run and that, to understand SoFi’s strategy, one needs to view SoFiUSD in the context of the company’s other infrastructure assets, namely, card issuer-processor Galileo.
Ron writes that “SoFiUSD will enable SoFi to serve as a stablecoin infrastructure provider for banks, fintechs, and enterprise platforms,” and argues that “SoFi Bank will use SoFiUSD to settle its own credit and debit transactions through Mastercard, while Galileo will provide fintechs with stablecoin settlement options via the card network.”
Alex, in his Fintech Takes newsletter, has a somewhat more cynical point of view (which I don’t disagree with!):
Put bluntly, there is no new, tangible benefit that SoFi members are going to get from SoFiUSD, based on what the company shared in its press release.
This makes me think that the real purpose of this press release is to appeal to SoFi investors, particularly the rabid contingent of retail traders that have made $SOFI a part of their identity.
And the fact that a savvy CEO like Anthony Noto apparently believes that this press release will positively impact those investors’ sentiment towards SoFi makes me depressed about the stock market, stablecoins, and the state of fintech overall.
Whatever happened to customer value, man?
In what could be interpreted as a sign of card-world incumbents seeking to blunt the threat posed by stablecoins to their business models, news circulated last week that Visa, Mastercard, Stripe, and possibly Coinbase are planning to team up to form a new consortium that would issue its own stablecoin.
The reports were light on details, but are notable nonetheless given the names involved. Stripe already has a significant presence in the stablecoin space, both through its stablecoin infrastructure subsidiary, Bridge, and through growing efforts to integrate stablecoins into its core payment processing business. Mastercard has its own stablecoin infrastructure play, Bridge-competitor BVNK, which Mastercard announced it would acquire earlier this year.
And, while Visa hasn’t made a high-profile acquisition á la Bridge or BVNK, it is very active in the stablecoin space, including an investment in BVNK and partnerships with Bridge, crypto card issuer Rain, crypto-as-a-service platform Baanx, as well as Visa’s own tokenization and stablecoin platforms.
The potential involvement of Coinbase is also notable, given Coinbase’s existing relationship with USDC-issuer Circle. More than a quarter of USDC in circulation is held on Coinbase, and Coinbase and Circle have a revenue sharing agreement that earned Coinbase approximately $1.35 billion in 2025.
Incumbent financial institutions aren’t taking the competitive threats posed by stablecoins lying down. Last week, the Wall Street Journal reported that the U.S. largest banks are working on creating a blockchain-based tokenized deposit network.
The Clearing House, a payments consortium co-owned by some of the country’s largest banks, will lead development and operations of the nascent effort, with a target launch date in “the first half of 2027,” according to the Wall Street Journal.
Tokenized deposits seem likely to serve a similar set of use cases as stablecoins, but, because they’re legally structured as deposits, are treated the same as commercial bank deposits for regulatory and accounting purposes. As bank deposits, customers also enjoy standard FDIC insurance coverage, unlike stablecoins, which lack such protections.
Last week also saw legacy remittance service MoneyGram and startup payroll and HR platform Deel launch their own stablecoin and wallet solutions.
MoneyGram describes its MGUSD as intended for users who need to move money, but may lack access to traditional financial services.
Beyond the primary use case of sending funds, MoneyGram also emphasized the potential for MGUSD to allow users to protect their purchasing power from unstable local currencies, saying in its announcement, “In many markets, consumers face inflation, currency instability or limited access to reliable financial services. MGUSD gives those customers a stable, dollar-denominated balance they can hold and access 24/7, as well as move globally and convert into local currency when they need it, on their own terms, at any time, from anywhere.”
While targeting a different segment of consumers, Deel’s announcement echoed MoneyGram’s narrative about enabling users in developing market economies to protect purchasing power by avoiding fees, punitive exchange rates, and inflation.
Deel’s DLUSD stablecoin and wallet allow contractors who are paid via Deel to choose to get paid, hold funds, earn “rewards,” and spend directly from a Deel stablecoin wallet.
Deel is beginning by rolling out the offering in Latin America, starting in inflation-plagued Argentina. The company plans to expand the offering to APAC, MENA, and Africa.
Finally, the Conference of State Bank Supervisors, a trade group that represents state financial regulators, published a comment letter last week encouraging the U.S. Treasury to “recalibrate” principles on the state licensing of stablecoin issuers under the GENIUS Act.
The GENIUS Act lays out a variety of pathways to being licensed as a “permitted payment stablecoin issuer,” including state licensing regimes. An individual state’s legal and regulatory framework, though, must be “substantially similar” to the federal framework.
The Stablecoin Certification Review Committee, a body called for by GENIUS that includes the Treasury Secretary, the Chair of the Federal Reserve (or the Vice Chair for Supervision), and the Chair of the FDIC, must approve each state’s regime as meeting or exceeding the requirements laid out in part 4(a) of the GENIUS Act.
Part 4(a) describes the requirements for permissible reserves, redemptions, reserve disclosures, the prohibition on rehypothecating reserves, capital, liquidity, and risk management, BSA/AML programs, and related topics.
CSBS’ comment letter argues that the Treasury Department’s proposed principles for determining when a state-level regulatory regime is substantially similar to the federal framework “improperly privilege the Office of the Comptroller of the Currency’s (“OCC”) stablecoin framework over the judgment and discretion of the states” in several critical areas.
CSBS argues that, “[i]f finalized in their current form, the proposed principles would swing stablecoin regulation in the United States toward a one-size-fits-all federal framework, threatening innovation in emerging stablecoin markets.”
Crime & Regulatory Round Up: Aspiration Cofounder Gets 14 Year Prison Sentence, GreenSky Settles State Suits for $10m, Wise Faces AML Scrutiny in Europe [Paying Subscriber Exclusive]
In fintech crime news, cofounder of “green” neobank Aspiration Joseph Sanberg was sentenced to 14 years in prison last week for his participation in a 5-year scheme to defraud lenders and investors of at least $248 million.