

Hey all, Jason here.
I had quite the attention double header yesterday: I caught a showing of The Odyssey (not on IMAX though), and made it home in time to nominally watch the very dramatic second half of the England-France World Cup match (ok, I did fall asleep before the end of the game, which England won despite the four goals France scored in the back half.) I swear, I’ll really make an effort to stay awake for tonight’s final match between Spain and Argentina, which kicks off at 9pm here in central European time.
The data on alternative credit is in
Partner content: Datos Insights surveyed 200 lenders and 1,500 consumers to see how traditional credit models are performing in today’s economy. The findings are clear: lenders increasingly don’t trust bureau data alone, but those who’ve added cash flow data are seeing measurable portfolio gains.
Inside the report:
The risk factors credit scores miss, and what’s hiding in plain sight
How leading lenders are moving beyond traditional credit data
How cash flow data is translating into better portfolio performance

Kraken Financial’s “Skinny” Master Account Still Isn’t Live, Its CEO Testified Last Week
The process governing Fed master accounts — who gets access, and what kind of diligence they must pass before they do so — remains not only a controversial topic, but one that continues to be exceptionally opaque.
Kraken Financial, a Wyoming-chartered special purpose depository institution, made headlines when it announced it was the first crypto-focused “tier 3” master account applicant to be approved this March.
But, the CEO of Kraken Financial, the company’s bank subsidiary, confirmed in testimony to a Wyoming legislative committee last week, the uninsured state-chartered special purpose depository institution is still “trying to get the account operationalized,” an indication of both the technical and political complexity of non-traditional firms gaining access to what is functionally publicly owned and operated financial infrastructure that historically has been fiercely guarded by incumbent financial institutions.
A traditional Fed master account is a depository account that an institution holds directly at one of the twelve regional Federal Reserve Banks. The accounts function as the ledger entries where an accountholder’s central bank money resides, are the mechanism through which institutions can borrow from the Fed discount window, and enable access to Federal Reserve-operated payment systems: FedWire, FedACH, and FedNow. (My friend and industry colleague Kiah Haslett has published multiple recent pieces on the topic of Fed master accounts.)
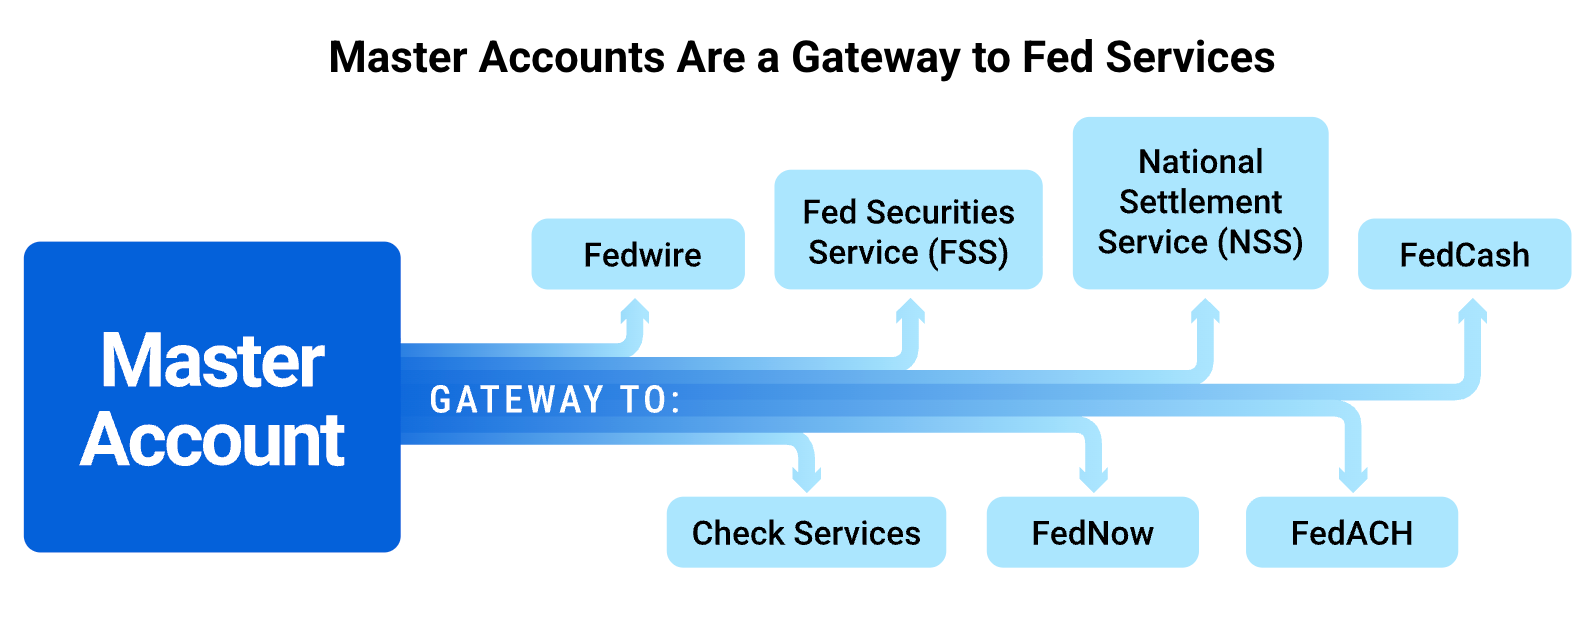
Entities that don’t qualify or choose not to maintain a Fed master account but wish to access these payment services typically do so through a correspondent relationship, meaning accessing these rails through an intermediary bank that does have a master account. This intermediation adds operational and counterparty risk, as well as cost.
As non-traditional financial institutions have grown in size, scope, and market share, the questions of who is eligible to apply for an account and how those applications are evaluated have multiplied.
In May 2021, the Federal Reserve Board released proposed guidelines for how Federal Reserve Banks would evaluate master account applications.
The guidelines enumerate five policy goals:
ensuring the safety and soundness of the banking system;
effectively implementing monetary policy;
promoting financial stability;
protecting consumers; and
promoting a safe, efficient, inclusive, and innovative payment system.
The initial 2021 guidance outlined “six principles” that the Federal Reserve said were (emphasis added) “intended to ensure that Reserve Banks evaluate a transparent and consistent set of factors.”
At a high level, the six principles described in that guidance include:
defining the institutions eligible to apply for a master account as “only those entities that are member banks or meet the definition of a depository institution under section 19(b) of the Federal Reserve Act.”
that “[p]rovision of an account and services to an institution should not present or create undue credit, operational, settlement, cyber or other risks to the Reserve Bank.”
that “[p]rovision of an account and services to an institution should not present or create undue credit, liquidity, operational, settlement, cyber or other risks to the overall payment system.”
that “[p]rovision of an account and services to an institution should not create undue risk to the stability of the U.S. financial system.”
that “[p]rovision of an account and services to an institution should not create undue risk to the overall economy by facilitating activities such as money laundering, terrorism financing, fraud, cybercrimes, or other illicit activity.”
and that “[p]rovision of an account and services to an institution should not adversely affect the Federal Reserve’s ability to implement monetary policy.”
The Fed updated its proposed guidelines in March 2022, supplementing the “six principles” framework with a three-tier framework for how Federal Reserve Banks would review master account applications from eligible institutions. The updated guidance was finalized and became effective on August 19, 2022.
The updated guidance defines “tier 1” as eligible institutions (Federal Reserve System member banks or entities that meet the definition of a depository institution under section 19(b) of the Federal Reserve Act) that are federally-insured.
Because, the guidance says, detailed regulatory and financial information would be easily available for this category of applicants, “access requests by Tier 1 institutions would generally be subject to a less intensive and more streamlined review.”
The guidance defines “tier 2” as entities subject to federal prudential supervision (eg federally chartered) that are not federally insured.
Because necessary regulatory and financial information to evaluate their risk may be less readily available, the guidance argues, tier 2 entities “would generally receive an intermediate level of review.”
The guidance defines “tier 3” entities as eligible institutions that are not subject to federal prudential supervision, which would include entities chartered as Wyoming Special Purpose Depository Institutions (Kraken, Custodia, Wyoming Deposit and Transfer Corporation, Commercium Financial), as Nebraska Digital Asset Depository Institutions (Telcoin), and as Connecticut Innovation Banks (Banking Circle US, Numisma, Moneycorp Bank US, Fnality Bank US).
National trust banks, which have surged in popularity among crypto and stablecoin firms in the wake of the passage of the GENIUS Act, would fall into tier 3, except in cases where they are part of a bank holding company that is subject to consolidate supervision from the Federal Reserve. (An earlier version of this post erroneously suggested that national trust banks would be considered tier 2.)
While less commonly discussed in the context of Fed master account access, tier 3 also would, presumably, include entities chartered as Georgia Merchant Acquiring Limited Purpose Banks (MALPBs), like Stripe, Checkout.com, and Fiserv.
But despite the existence of “tier 3” as a category of eligible applicant with ostensibly defined criteria for evaluating applications from such institutions, it has proven functionally impossible for nearly all tier 3 entities that have tried to actually win access to and operationalize a Fed master account.
Custodia is arguably the canonical example of a tier 3 institution’s quixotic quest for master account access. Custodia, a Wyoming-chartered special purpose depository institution, is in the midst of a long-running lawsuit against the Federal Reserve Board of Governors and the Federal Reserve Bank of Kansas City over the latter’s refusal to grant Custodia master account access. Last week, Custodia filed a certiorari petition, asking the Supreme Court to review a March ruling by the 10th Circuit Court of Appeals upholding prior rulings in the Fed’s favor.
Current Fed Vice Chair of Supervision Michelle Bowman has seemingly acknowledged the near-impossibility of tier 3 entities obtaining master account access.
This March, during a Q&A at an American Bankers Association event, ABA Chair Kenneth Kelly asked Bowman a two-part question about how the Federal Reserve planned to evaluate stablecoin-related national trust banks’ potential applications for master account access and specifically about why Kraken’s application was approved before regulations defining the so-called “skinny” master account were finalized.
Bowman described the topic of master accounts as Federal Reserve Governor Waller’s “space,” and reiterated the typical process by which the twelve Federal Reserve Banks evaluate such applications, adding (beginning at minute 0:26), “That third level… was a little bit like, I like to say ‘unobtainium,’ right, you just can’t qualify, it’s not, it doesn’t work.”
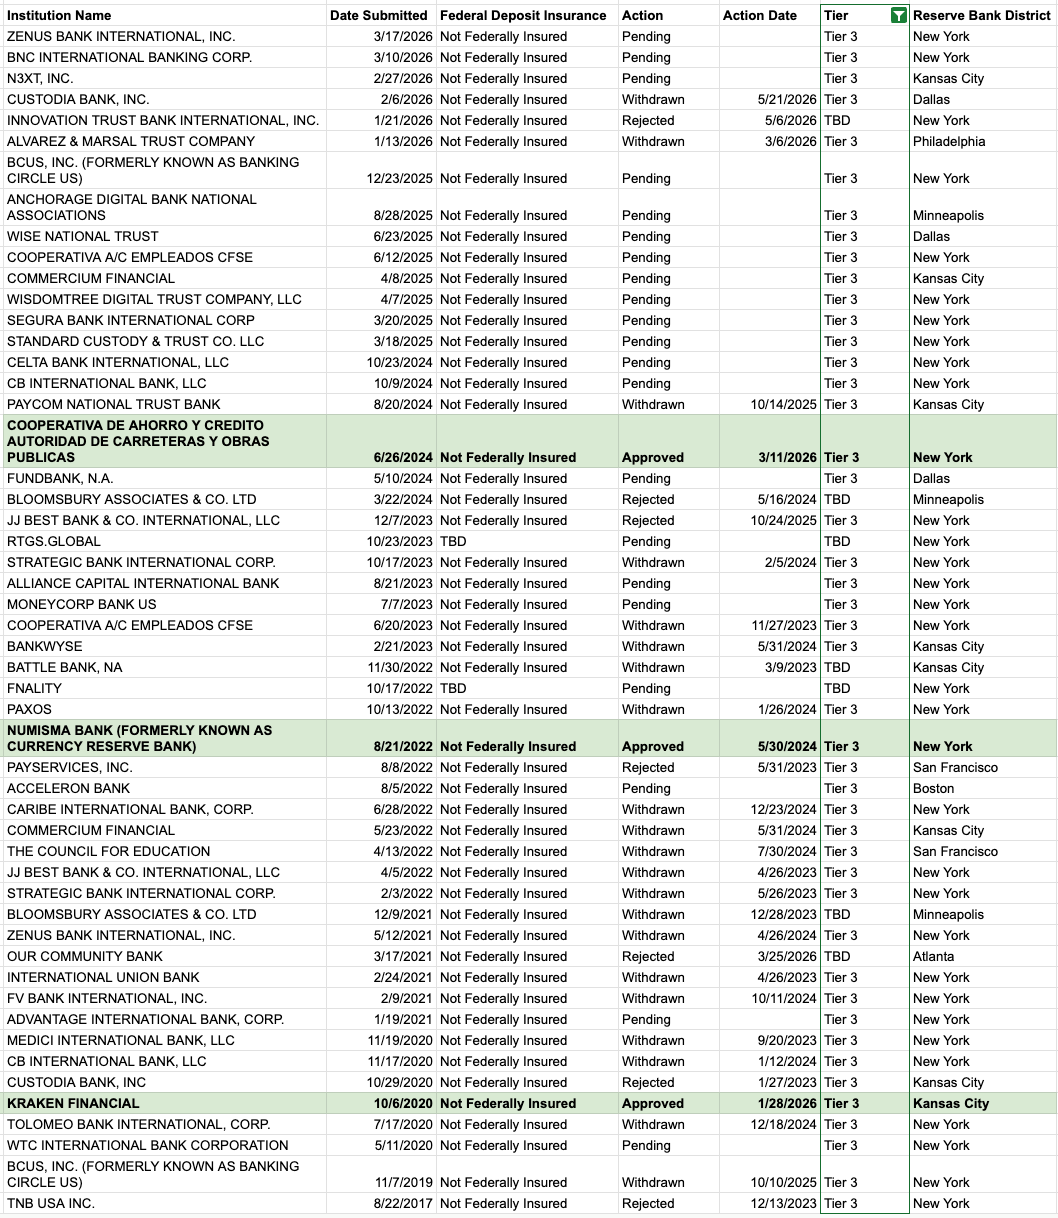
The data bear out Bowman’s point. Of 53 tier 3 or “TBD” tier applicants, only three have been approved: the Cooperativa de la Autoridad de Carreteras y Obras Publicas, which is chartered under Puerto Rico law and insured by Corporation for the Supervision and Insurance of Cooperatives of Puerto Rico, rather than the FDIC; Numisma Bank, whose business model focuses on the wholesale distribution of US and foreign bank notes; and Kraken.
Addressing Kraken’s application specifically at the ABA event, Bowman said, “The thought process came out that, that perhaps there’s a way that we could test whether or not this could work. So, the way that Kansas City approached approving that application was on a limited basis for a very narrow opportunity for access and on a time, a time certain timeframe. I kind of think about it that as a pilot, um, it’s only accessible for this one institution, and so, I think that’s how we’re trying to learn from that experience to understand how we should think about the RFI that we published and how that could feed into whatever decisions might be made later in the year. But that’s probably something you’d want to talk to Governor Waller a little bit more specifically about.”
The “skinny” account Bowman mentioned was first floated by Waller last October. An initial request for information was published on December 23, 2025, and proposed revisions to the guidelines for account access and service requests were published on May 26, 2026. The comment deadline for the proposed revisions is next Monday, July 27th.
The Federal Reserve Board has “encouraged” Reserve Banks to “pause” decisions on tier 3 applications in the meantime.
A May 2026 press release and staff memo said in part, “To promote greater clarity and consistency, the Board is also encouraging Reserve Banks to temporarily pause decisions on access requests from institutions that fall within Tier 3 of the Board’s Account Access Guidelines until the Board has completed its policy development process on the payment account proposal. The temporary pause will allow the Federal Reserve to solicit and consider public input on payment accounts and to promote consistent implementation.”
Kraken’s Master Account Is Not Yet Operationalized
Setting aside the relatively idiosyncratic approvals for Numisma and Cooperativa de la Autoridad de Carreteras y Obras Publicas, Kraken is the only other tier 3 institution to win access, and is the only one focused on a digital asset business model.
The company announced the news this March, saying at the time:
“We are excited to announce that Kraken Financial, our Wyoming-chartered bank, has been granted a Federal Reserve master account. The approval makes Kraken Financial the first digital asset bank in U.S. history to gain direct access to the Federal Reserve’s payment infrastructure.
The decision marks a major milestone and underscores years of sustained regulatory engagement, operational rigor, and close coordination with U.S. and Wyoming supervisors. It further strengthens Payward’s unified infrastructure model by integrating Federal Reserve connectivity directly into the platform’s settlement and payments layer.”
The Federal Reserve Bank of Kansas City, which approved Kraken’s application, described the approval as for “a limited purpose account for an initial term of one year that includes restrictions and limitations tailored for Kraken Financial’s business model and risk profile that are appropriate to mitigate risks identified in the Guidelines.”
Beyond describing Kraken’s account as “limited purpose,” the Kansas City Fed declined to elaborate on what Kraken would or would not have access to, saying, “Due to the confidentiality of business information provided by applicants, the Kansas City Fed does not disclose specific information about account holders’ access to the range of Federal Reserve financial services.”
While the news was officially announced in March, the approval date reflected in the Fed’s master account database is January 28, 2026.
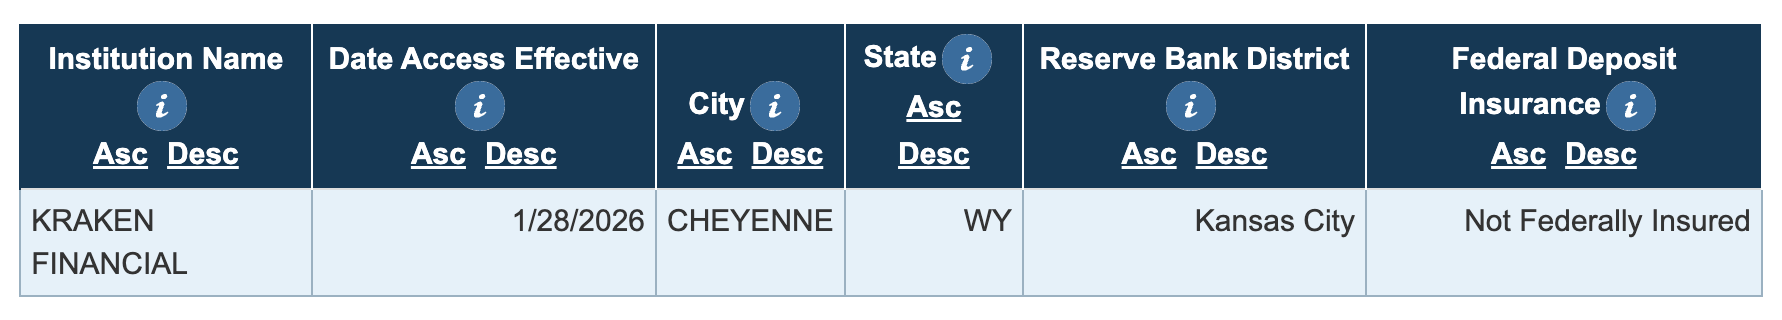
The “Date Access Effective” is, per the Fed’s site, defined as “the date on which Federal Reserve systems indicate an institution began to access a Reserve Bank master account and financial services.”
Per Kraken’s website and customer-facing user interface, wires continue to be processed through Dart Bank, though institutions that settle and clear through a correspondent’s master account would still be listed on the Fed’s database of those with “existing access.”
According to the Fed’s site, “The Existing Access database consists of financial institutions that have access to Reserve Bank financial services. These institutions either have their own Reserve Bank master account or access Reserve Bank financial services by settling transactions in the master account of another depository institution.”
What is now clear, based on testimony from Brian Mathena, the CEO of Kraken’s bank subsidiary Kraken Financial, in front of the Wyoming Select Committee on Blockchain, Financial Technology and Digital Innovation Technology last week, is that Kraken’s own master account is not yet operational.
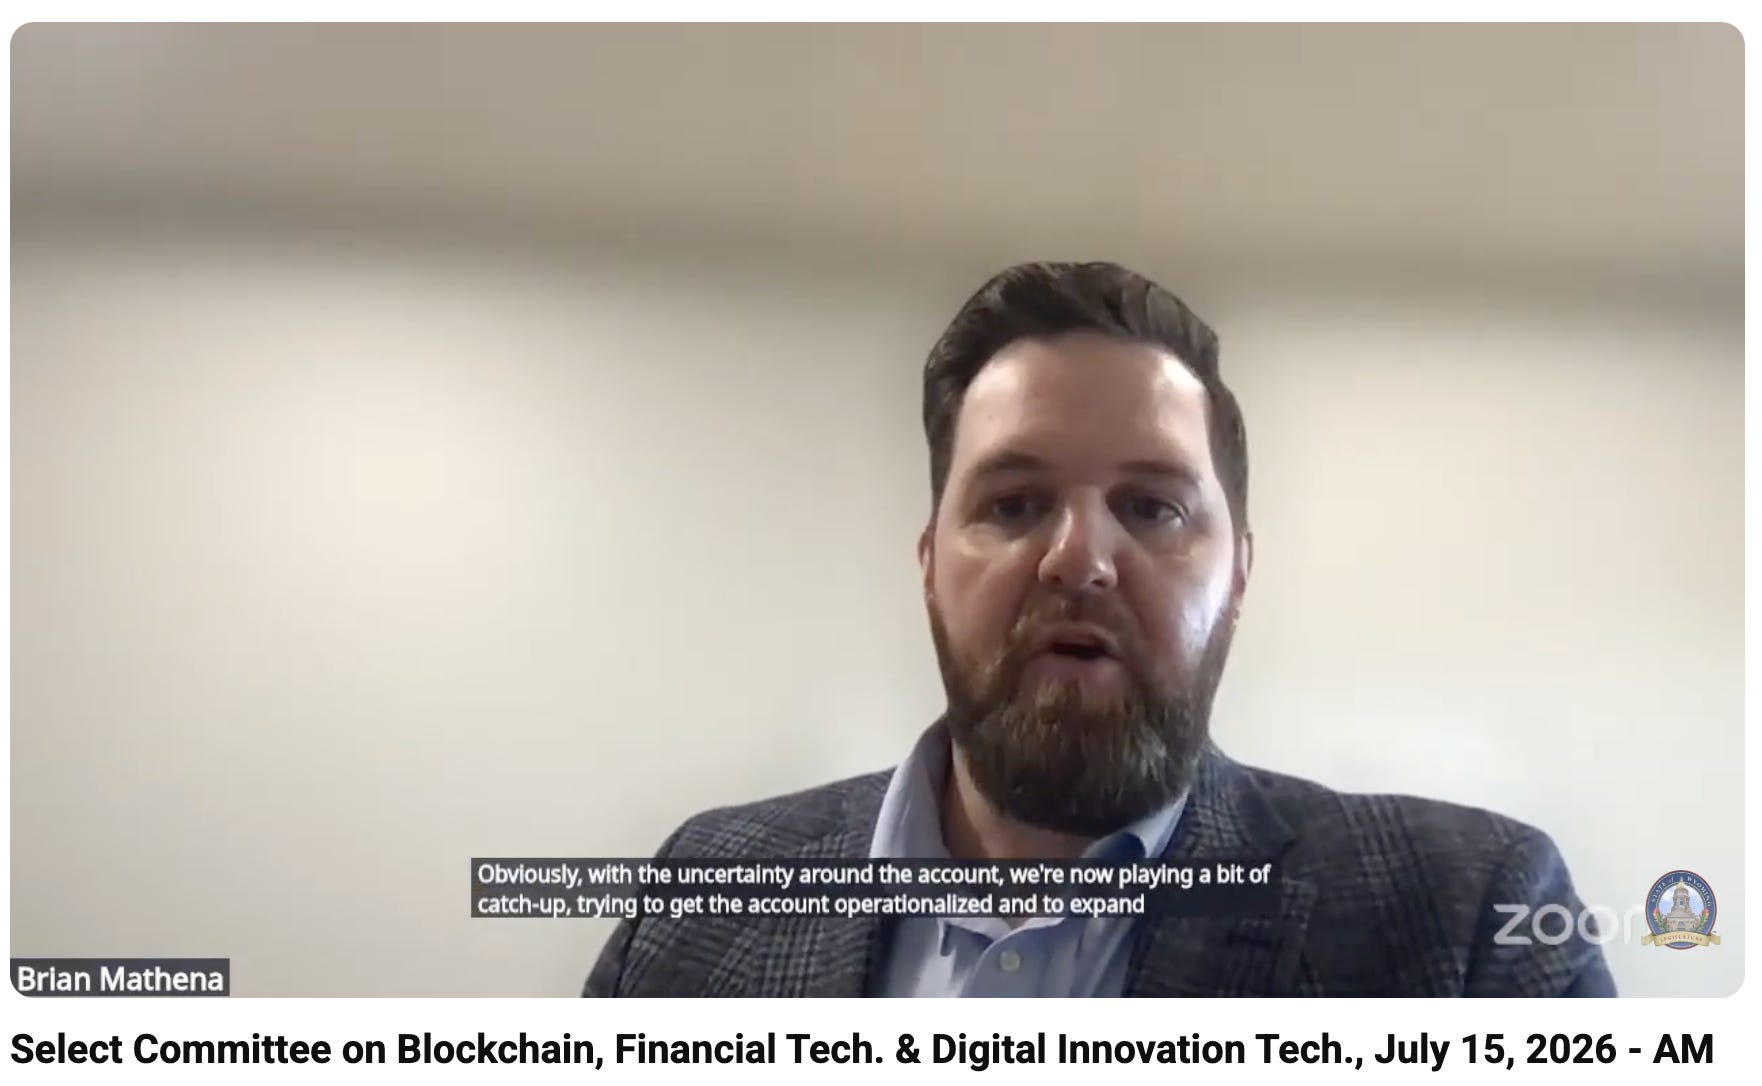
Mathena said in part, “The big news this year was that we received our Fed master account, so plenty of news and attention around that. That was certainly, you know, a very long process for us, and something we spent quite a bit of time on as a team. We’re very excited and proud to be in a position where that account was issued to us. Obviously with the uncertainty around the account, we’re now playing a bit of catch up, trying to get the account operationalized and to expand our deposit product and be able to more fully leverage the Fed master account. So that’s something that will still be coming here in the near future.”
Despite Emphasizing “Transparency,” Process Is Anything But
The Fed master account issue can feel like a particularly pedantic one.
But it represents (at least) two fundamental questions: who gets access to publicly owned and operated payment infrastructure, and who gets to decide who gets access?
The bulk of recent debate about “Fed independence” has focused on the Federal Reserve Board of Governors and, understandably, interest rate policy decisions.
But, as alluded to above, master account decisions are ostensibly made by the twelve Federal Reserve Banks — not the Federal Reserve Board. The Federal Reserve Banks are legally structured as federally chartered private corporations that are owned by their member banks.
Each Reserve Bank has a nine-member board of directors, with three directors elected by member banks to represent the commercial banking industry, three elected by member banks to represent “the public,” and three appointed by the Federal Reserve Board of Governors, also to represent “the public,” where “the public” entails “due but not exclusive consideration to the interests of agriculture, commerce, industry, services, labor, and consumers.”
Given that the twelve individual Federal Reserve Banks that are legally empowered to decision master account applications are owned by and, largely, controlled by their member banks, it shouldn’t be entirely surprising that non-traditional tier 2 and especially tier 3 applicants face an uphill climb in being approved — “unobtainium,” as Fed Vice Chair for Supervision Bowman put it.
Beyond the obvious potential for conflicts of interest, there’s also the logistical question of coordinating standards and processes for evaluating applications across the twelve member banks: how should applications be evaluated, what are the specific criteria for approval, and so forth — which the proposed revisions to the Fed’s policy on payment system risk and guidelines for account and services requests attempt to address.
Trump’s recent executive order also touched on these issues. The May E.O. explicitly requested that the Federal Reserve Board evaluate:
the legal, regulatory, and policy framework governing access to Reserve Bank payment accounts and payment services by uninsured depository institutions and non-bank financial companies, including those engaged in digital assets and other novel financial activities;
the legal authority of the Federal Reserve, under the Federal Reserve Act and other applicable Federal law, to extend direct access to Federal Reserve payment accounts and payment services to covered firms; and
whether, and if so to what extent, each of the 12 Federal Reserve Banks has legal authority to act independently of the FRB in granting or denying access to Reserve Bank payment accounts and payment services and, if independent action and decisions by individual Federal Reserve Banks is legally permissible, what FRB-level regulations or policies the FRB has established or proposes to establish to ensure that covered firms are evaluated on a consistent basis regardless of which Federal Reserve Bank receives or processes their applications.
For close observers of the master account issue, it’s clear that battle lines have been drawn. How the fight for access plays out and who the “winners” and “losers” are, though, remains to be seen.
Unified Identity for Compliance with PCI, GDPR, DORA, and Regional Banking Regulations
Partner content: Compliance requirements mandate complete, identity-attributable audit trails of all access to your environments.
Teleport records every session with command-level logging tied to a cryptographically verifiable identity, and unifies the identity chain from IdP through cloud, code, and infrastructure access into one investigation view. AI-generated timelines reconstruct incidents in minutes, so when the auditors ask, you can provide answers right away without stitching evidence from siloed logs.
As audits get harder and regulations multiply, teams using Teleport report up to 80% less time spent on access troubleshooting and audit preparation. Help your team stay ahead.

Trump-Linked Fintech’s Potential Acquirer Terminates LOI, NYBNPL, Visa Launches Stablecoin Platform, Another Tiny Bank Fails [Paid Subscriber Exclusive]
On July 7th, Perpetuals.com announced it had signed a non-binding letter of intent to explore the potential acquisition of a subsidiary of Trump-linked crypto and stablecoin platform AI Financial Corporation (previously known as ALT5 Sigma). Perpetuals.com said that it was conducting due diligence and that “no decisions [had] been made.”
But a week later — and just two days after Fintech Business Weekly reported that a subsidiary of AI Financial Corp doing business under the names “MSwipe” and “Stradacarte” offers so-called “no KYC” cards and has been linked to a service marketed for sanctions evasion — Perpetuals.com announced it had abruptly terminated the letter of intent with AI Finanical Corp.